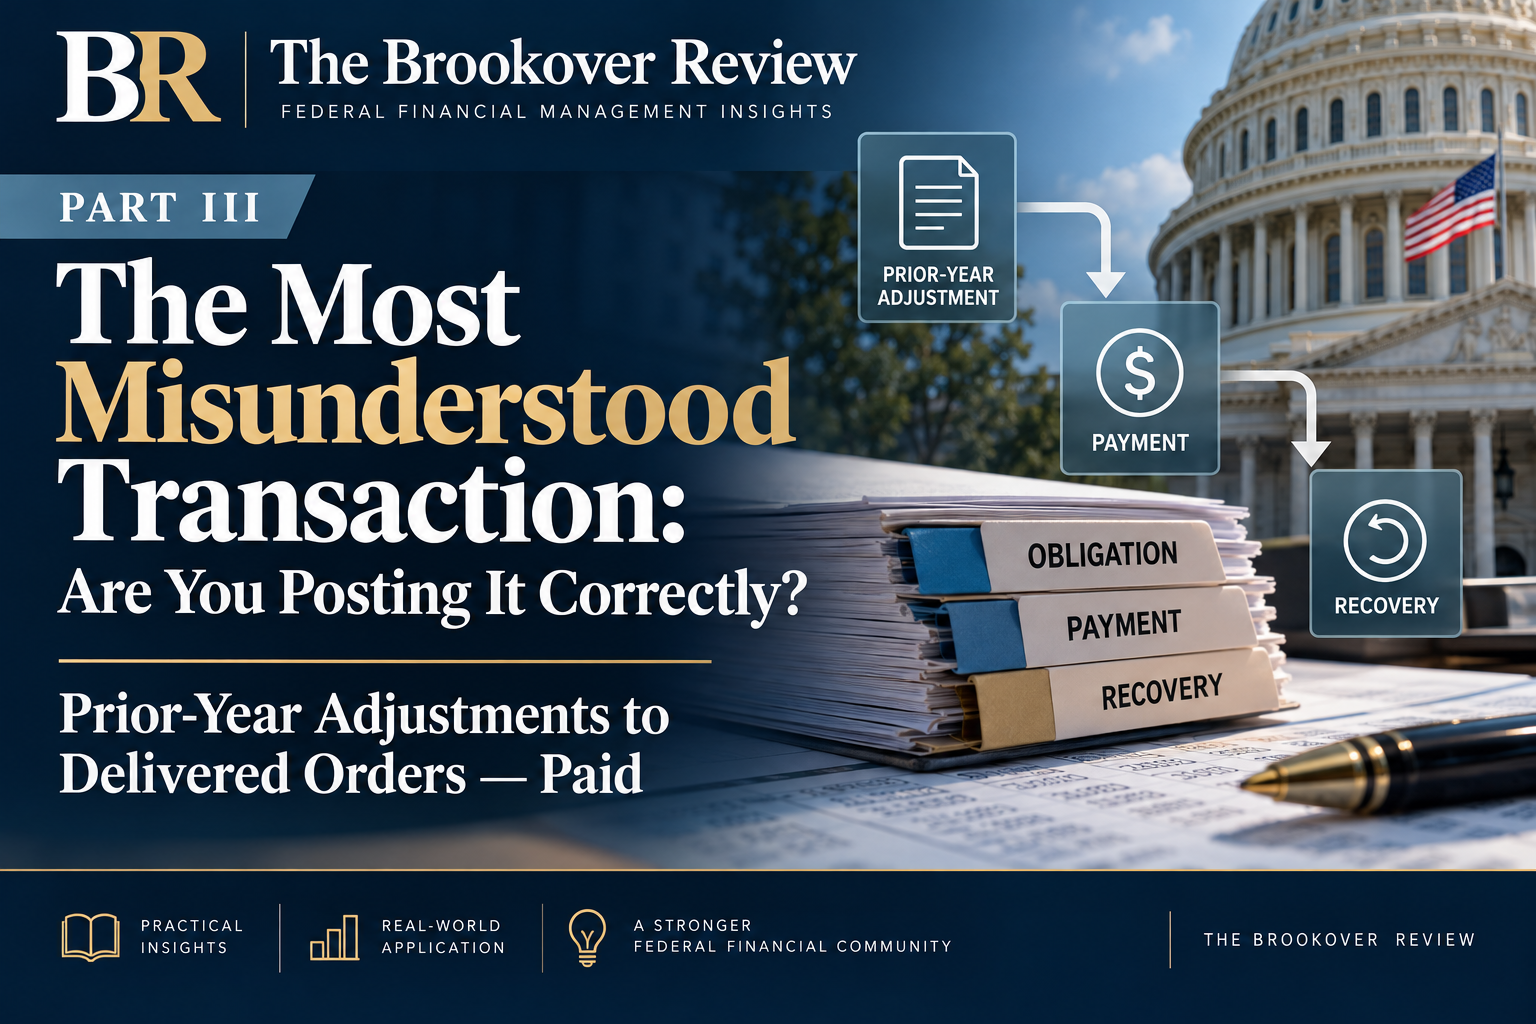
Part III: Prior-Year Adjustments to Delivered Orders — Paid
Editor's Note: The prior-year adjustment accounts discussed in this article are used when an obligation recorded in a previous fiscal year is adjusted in a subsequent fiscal year. If the obligation, accrual, or payment is adjusted within the same fiscal year in which it was originally recorded, the original USSGL account is adjusted directly rather than using the separate prior-year upward or downward adjustment accounts.
An obligation eventually reaches the final stage of its financial lifecycle.
The goods have been received or the services performed. The government has recognized its liability. Payment is made, and the liability is extinguished.
But what happens when the amount changes after payment?
What happens when the government discovers it paid too much, or when an authorized adjustment establishes that additional payment is required?
In Part I, we examined prior-year adjustments to undelivered orders. Part II followed delivered orders that remained unpaid, demonstrating how adjustments affect both budgetary and proprietary accounting.
Now we follow those obligations through payment and recovery.
The obligation may be the same. Its accounting status is not.
From Unpaid to Paid: The Accounts That Matter
In Part II, we worked through two examples: services funded by expired authority and capitalized software funded by authority that remained available.
Both ended with a $300 liability, but their underlying accounting differed.
Part III introduces three budgetary accounts that distinguish paid obligations from their unpaid counterparts.
| USSGL | Account |
|---|---|
| 490200 | Delivered Orders — Obligations, Paid |
| 497200 | Downward Adjustments of Prior-Year Paid Delivered Orders — Obligations, Refunds Collected |
| 498200 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Paid |
We will also use 310710 — Unexpended Appropriations — Used — Disbursed and 570010 — Expended Appropriations — Disbursed to distinguish payment activity from previously accrued appropriations.
The central principle remains unchanged:
The original obligation and its subsequent adjustments must remain distinguishable, even after payment.
Example 1: Paying a Prior-Year Upward Adjustment Under Expired Authority
Fund 1112222-2525 — Expired Authority
In Part II, the agency accrued $250 for services received before year-end.
During the following fiscal year, additional information established that the services cost $100 more than originally estimated. The agency recognized the additional obligation and liability as a prior-year upward adjustment.
A subsequent $50 downward adjustment reduced the amount owed.
The result was a $300 unpaid liability.
Now the agency is ready to pay.
Beginning Trial Balance
The following balances carry forward from Part II.
| USSGL | Account | Beginning | Activity | Ending |
|---|---|---|---|---|
| Budgetary Accounts | ||||
| 420100 | Total Actual Resources — Collected | $1,000 | $0 | $1,000 |
| 465000 | Allotments — Expired Authority | ($450) | $0 | ($450) |
| 480100 | Undelivered Orders — Obligations, Unpaid | ($250) | $0 | ($250) |
| 490100 | Delivered Orders — Obligations, Unpaid | ($250) | $0 | ($250) |
| 497100 | Downward Adjustments of Prior-Year Unpaid Delivered Orders — Obligations, Recoveries | $50 | $0 | $50 |
| 498100 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Unpaid | ($100) | $0 | ($100) |
| Budgetary Total | $0 | $0 | $0 | |
| USSGL | Account | Beginning | Activity | Ending |
| Proprietary Accounts | ||||
| 101000 | Fund Balance With Treasury | $1,000 | $0 | $1,000 |
| 211000 | Accounts Payable | ($300) | $0 | ($300) |
| 310000 | Unexpended Appropriations - Cumulative | ($750) | $0 | ($750) |
| 310700 | Unexpended Appropriations — Used | $50 | $0 | $50 |
| 570000 | Expended Appropriations | ($50) | $0 | ($50) |
| 610000 | Operating Expenses/Program Costs | $50 | $0 | $50 |
| Proprietary Total | $0 | $0 | $0 | |
For readability throughout these examples, debit balances are presented as positive amounts and credit balances are presented in parentheses as negative amounts.
The budgetary accounts preserve the original $250 delivered order, the $100 upward adjustment, and the $50 downward adjustment.
Together, they explain the $300 liability.
Recording the $300 Payment
Of the $300 disbursement, $100 relates to the previously accrued upward adjustment. The remaining $200 represents the original delivered order after the $50 downward adjustment.
Budgetary Entry
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 498100 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Unpaid | $100 | $0 |
| 490100 | Delivered Orders — Obligations, Unpaid | $200 | $0 |
| 498200 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Paid | $0 | $100 |
| 490200 | Delivered Orders — Obligations, Paid | $0 | $200 |
| Total | $300 | $300 | |
The upward adjustment moves from 498100 to 498200. The remaining original obligation moves from 490100 to 490200.
The existing $50 in 497100 is not transferred to 497200 because the downward adjustment occurred before payment. No refund of previously disbursed funds was collected.
Proprietary Entry — Payment
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 211000 | Accounts Payable | $300 | $0 |
| 101000 | Fund Balance With Treasury | $0 | $300 |
| Total | $300 | $300 | |
Accounts Payable is extinguished, and Fund Balance With Treasury decreases by $300.
No additional expense is recognized because the liability was previously accrued.
Recognizing Disbursed Appropriations
The corresponding appropriations activity must also reflect payment.
Proprietary Entry — Appropriations
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 310710 | Unexpended Appropriations — Used — Disbursed | $300 | $0 |
| 570000 | Expended Appropriations | $300 | $0 |
| 310700 | Unexpended Appropriations — Used | $0 | $300 |
| 570010 | Expended Appropriations — Disbursed | $0 | $300 |
| Total | $600 | $600 | |
This reclassifies the appropriations activity from accrued to disbursed status without creating another obligation or reducing Fund Balance With Treasury again.
What if the Upward Adjustment Was Not Previously Accrued?
Our example assumes the $100 upward adjustment was recognized as an unpaid liability before payment.
However, an agency may identify an additional amount owed on a prior-year delivered order and record the adjustment directly in paid status.
In that circumstance, the upward adjustment may be recorded directly in 498200 without first passing through 498100.
The proprietary entry would reflect the underlying economic event and disbursement, potentially involving an expense or asset and Fund Balance With Treasury.
The distinction is whether the upward adjustment was previously accrued or recognized directly in paid status.
Join the Practitioners Reading Ahead
Independent, practitioner-written analysis on federal finance, systems, and audit readiness — delivered before it hits your feed.
Ending Trial Balance
| USSGL | Account | Beginning | Activity | Ending |
|---|---|---|---|---|
| Budgetary Accounts | ||||
| 420100 | Total Actual Resources — Collected | $1,000 | $0 | $1,000 |
| 465000 | Allotments — Expired Authority | ($450) | $0 | ($450) |
| 480100 | Undelivered Orders — Obligations, Unpaid | ($250) | $0 | ($250) |
| Unpaid Delivered Orders | ||||
| 490100 | Delivered Orders — Obligations, Unpaid | ($250) | $200 | ($50) |
| 497100 | Downward Adjustments of Prior-Year Unpaid Delivered Orders — Obligations, Recoveries | $50 | $0 | $50 |
| 498100 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Unpaid | ($100) | $100 | $0 |
| Paid Delivered Orders | ||||
| 490200 | Delivered Orders — Obligations, Paid | $0 | ($200) | ($200) |
| 498200 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Paid | $0 | ($100) | ($100) |
| Budgetary Total | $0 | $0 | $0 | |
| USSGL | Account | Beginning | Activity | Ending |
| Proprietary Accounts | ||||
| 101000 | Fund Balance With Treasury | $1,000 | ($300) | $700 |
| 211000 | Accounts Payable | ($300) | $300 | $0 |
| 310000 | Unexpended Appropriations - Cumulative | ($750) | $0 | ($750) |
| 310700 | Unexpended Appropriations — Used | $50 | ($300) | ($250) |
| 310710 | Unexpended Appropriations — Used — Disbursed | $0 | $300 | $300 |
| 570000 | Expended Appropriations | ($50) | $300 | $250 |
| 570010 | Expended Appropriations — Disbursed | $0 | ($300) | ($300) |
| 610000 | Operating Expenses/Program Costs | $50 | $0 | $50 |
| Proprietary Total | $0 | $0 | $0 | |
Notice that 490100 retains a $50 credit balance, while 497100 retains a $50 debit balance.
Together, those accounts net to zero.
The original unpaid delivered-order position is settled, while the paid accounts preserve the separate $200 original payment and $100 upward-adjustment payment.
A Note on Abnormal Balances
The ending balances in 310700 and 570000 are opposite their normal orientations.
This results from our simplified scenario carrying forward only $50 of net accrued appropriations activity while recording a $300 payment.
We have excluded additional current-year accrual activity that might otherwise affect those balances.
The accounts remain offsetting, as do 310710 and 570010.
An abnormal balance does not automatically establish an accounting error. However, offsetting balances alone do not guarantee acceptance under GTAS validation rules.
The agency must be able to support the underlying accrual history and satisfy the applicable reporting requirements.
Our example illustrates the payment mechanics rather than a complete agency-level trial balance.
Example 2: Recovering a Prior-Year Payment Through Accounts Receivable
Fund 3334444 — 2526/No-Year — Available Authority
Our second example returns to the capitalized software transaction from Part II.
The government recognized $300 in Internal Use Software and a corresponding $300 liability.
As in Example 1, the original $250 delivered order was increased by $100 and subsequently reduced by $50.
After paying the $300 liability, the agency discovers an additional $50 overcharge.
The vendor agrees to refund the amount, but payment is not immediately received.
The government has established a right to recover $50, but it has not yet collected the funds.
Beginning Trial Balance
| USSGL | Account | Beginning | Activity | Ending |
|---|---|---|---|---|
| Budgetary Accounts | ||||
| 420100 | Total Actual Resources — Collected | $1,000 | $0 | $1,000 |
| 461000 | Allotments — Realized Resources | ($450) | $0 | ($450) |
| 480100 | Undelivered Orders — Obligations, Unpaid | ($250) | $0 | ($250) |
| 490100 | Delivered Orders — Obligations, Unpaid | ($250) | $0 | ($250) |
| 497100 | Downward Adjustments of Prior-Year Unpaid Delivered Orders — Obligations, Recoveries | $50 | $0 | $50 |
| 498100 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Unpaid | ($100) | $0 | ($100) |
| Budgetary Total | $0 | $0 | $0 | |
| USSGL | Account | Beginning | Activity | Ending |
| Proprietary Accounts | ||||
| 101000 | Fund Balance With Treasury | $1,000 | $0 | $1,000 |
| 183000 | Internal Use Software | $300 | $0 | $300 |
| 211000 | Accounts Payable | ($300) | $0 | ($300) |
| 310000 | Unexpended Appropriations - Cumulative | ($750) | $0 | ($750) |
| 310700 | Unexpended Appropriations — Used | $50 | $0 | $50 |
| 331000 | Cumulative Results of Operations | ($250) | $0 | ($250) |
| 570000 | Expended Appropriations | ($50) | $0 | ($50) |
| Proprietary Total | $0 | $0 | $0 | |
| USSGL | Account | Beginning | Activity | Ending |
| Memorandum Accounts | ||||
| 880100 | Offset for Purchases of Assets | ($50) | $0 | ($50) |
| 880200 | Purchases of Property, Plant, and Equipment | $50 | $0 | $50 |
880100 and 880200 are non-add, off-budget memorandum accounts used to track current-year purchases of Property, Plant, and Equipment (USSGL transaction G120). Internal use software meeting capitalization criteria is classified as General PP&E under FASAB's SFFAS 10 and SFFAS 6. Their beginning balances carry forward the net $50 upward adjustment recorded against the software purchase in Part II and are not included in the Budgetary or Proprietary Totals above.
Paying the Existing Liability
The agency first pays the outstanding $300.
Combined Budgetary Entry
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 498100 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Unpaid | $100 | $0 |
| 490100 | Delivered Orders — Obligations, Unpaid | $200 | $0 |
| 498200 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Paid | $0 | $100 |
| 490200 | Delivered Orders — Obligations, Paid | $0 | $200 |
| Total | $300 | $300 | |
Combined Proprietary Entries
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 211000 | Accounts Payable | $300 | $0 |
| 101000 | Fund Balance With Treasury | $0 | $300 |
| 310710 | Unexpended Appropriations — Used — Disbursed | $300 | $0 |
| 570000 | Expended Appropriations | $300 | $0 |
| 310700 | Unexpended Appropriations — Used | $0 | $300 |
| 570010 | Expended Appropriations — Disbursed | $0 | $300 |
| Total | $900 | $900 | |
The liability is extinguished. Fund Balance With Treasury decreases to $700, while Internal Use Software remains at $300.
The existing $50 downward adjustment remains in 497100 because it was recognized before payment.
Establishing the Refund Receivable
After payment, the agency identifies an additional $50 overcharge and establishes a receivable.
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 131000 | Accounts Receivable | $50 | $0 |
| 183000 | Internal Use Software | $0 | $50 |
| Total | $50 | $50 | |
The agency recognizes its claim against the vendor and reduces the software asset from $300 to $250.
There is no budgetary entry under the posting logic used here, and Fund Balance With Treasury remains unchanged.
Recognizing a receivable is not the same as collecting a refund.
Collecting the $50 Refund
The vendor subsequently returns the $50.
For this illustration, we assume the recovered authority is subject to apportionment and was not previously anticipated.
Budgetary Entry
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 497200 | Downward Adjustments of Prior-Year Paid Delivered Orders — Obligations, Refunds Collected | $50 | $0 |
| 445000 | Unapportioned — Unexpired Authority | $0 | $50 |
| Total | $50 | $50 | |
The debit to 497200 identifies the collection as a downward adjustment to a prior-year paid delivered order.
The credit to 445000 reflects the assumed treatment of recovered authority as unapportioned.
Proprietary Entry — Collection
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 101000 | Fund Balance With Treasury | $50 | $0 |
| 131000 | Accounts Receivable | $0 | $50 |
| Total | $50 | $50 | |
The collection increases Fund Balance With Treasury and extinguishes the receivable.
Internal Use Software is not reduced again because the asset adjustment was recognized when the receivable was established.
Reversing Appropriations and Memorandum Activity
The refund also requires the applicable reversals of disbursed appropriations and asset-purchase memorandum activity.
Proprietary Entry — Appropriations Reversal
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 570010 | Expended Appropriations — Disbursed | $50 | $0 |
| 310710 | Unexpended Appropriations — Used — Disbursed | $0 | $50 |
| Total | $50 | $50 | |
Memorandum Entry — Asset Purchase Reversal
| USSGL | Account | Debit | Credit |
|---|---|---|---|
| 880100 | Offset for Purchases of Assets | $50 | $0 |
| 880200 | Purchases of Property, Plant, and Equipment | $0 | $50 |
| Total | $50 | $50 | |
The appropriations reversal reduces the net disbursed amount. The memorandum reversal reduces the associated asset-purchase activity.
Neither duplicates the reduction to Internal Use Software already recognized when the receivable was established.
Ending Trial Balance
| USSGL | Account | Beginning | Activity | Ending |
|---|---|---|---|---|
| Budgetary Accounts | ||||
| 420100 | Total Actual Resources — Collected | $1,000 | $0 | $1,000 |
| 445000 | Unapportioned — Unexpired Authority | $0 | ($50) | ($50) |
| 461000 | Allotments — Realized Resources | ($450) | $0 | ($450) |
| 480100 | Undelivered Orders — Obligations, Unpaid | ($250) | $0 | ($250) |
| Unpaid Delivered Orders | ||||
| 490100 | Delivered Orders — Obligations, Unpaid | ($250) | $200 | ($50) |
| 497100 | Downward Adjustments of Prior-Year Unpaid Delivered Orders — Obligations, Recoveries | $50 | $0 | $50 |
| 498100 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Unpaid | ($100) | $100 | $0 |
| Paid Delivered Orders | ||||
| 490200 | Delivered Orders — Obligations, Paid | $0 | ($200) | ($200) |
| 497200 | Downward Adjustments of Prior-Year Paid Delivered Orders — Obligations, Refunds Collected | $0 | $50 | $50 |
| 498200 | Upward Adjustments of Prior-Year Delivered Orders — Obligations, Paid | $0 | ($100) | ($100) |
| Budgetary Total | $0 | $0 | $0 | |
| USSGL | Account | Beginning | Activity | Ending |
| Proprietary Accounts | ||||
| 101000 | Fund Balance With Treasury | $1,000 | ($250) | $750 |
| 131000 | Accounts Receivable | $0 | $0 | $0 |
| 183000 | Internal Use Software | $300 | ($50) | $250 |
| 211000 | Accounts Payable | ($300) | $300 | $0 |
| 310000 | Unexpended Appropriations - Cumulative | ($750) | $0 | ($750) |
| 310700 | Unexpended Appropriations — Used | $50 | ($300) | ($250) |
| 310710 | Unexpended Appropriations — Used — Disbursed | $0 | $250 | $250 |
| 331000 | Cumulative Results of Operations | ($250) | $0 | ($250) |
| 570000 | Expended Appropriations | ($50) | $300 | $250 |
| 570010 | Expended Appropriations — Disbursed | $0 | ($250) | ($250) |
| Proprietary Subtotal | $0 | $0 | $0 | |
| USSGL | Account | Beginning | Activity | Ending |
| Memorandum Accounts | ||||
| 880100 | Offset for Purchases of Assets | ($50) | $50 | $0 |
| 880200 | Purchases of Property, Plant, and Equipment | $50 | ($50) | $0 |
131000 shows a net $0 Activity because the $50 receivable established mid-period was fully collected before period end. 310710 and 570010 reflect the net $250 disbursed after the $50 appropriations reversal. 880100 and 880200 are non-add, off-budget memorandum accounts and are not included in the Budgetary or Proprietary Totals; the $50 reversal returns both accounts to $0, consistent with Internal Use Software settling back to its original $250 basis.
The agency has now paid $300 and recovered $50.
Internal Use Software is valued at $250, Accounts Payable and Accounts Receivable are zero, and Fund Balance With Treasury is $750.
The disbursed appropriations accounts reflect the net $250 disbursement.
Why Recoveries Matter Under Multi-Year and No-Year Authority
Our second example illustrates an important distinction:
Recovering funds and having authority to obligate those funds are not necessarily the same thing.
Fund 3334444 represents multi-year or no-year authority that remains available for obligation.
Unlike expired authority, where recoveries generally remain available only for properly chargeable adjustments and payments, recoveries under unexpired authority may support new obligations, subject to legal and funds-control requirements.
But availability does not mean unrestricted use.
In our example, the $50 refund was credited to 445000 — Unapportioned — Unexpired Authority.
The agency recovered $50, but that amount is not automatically available within its existing allotment.
The applicable SF-132 apportionment, including any provisions governing recoveries, determines whether the agency may use those resources without additional apportionment action.
Where recoveries are exempt from apportionment, the accounting treatment may differ.
Obligating recovered funds without the necessary authority can create an Antideficiency Act concern, even when the underlying appropriation remains unexpired.
Fund Balance With Treasury does not, by itself, establish available budgetary authority.
That is why recoveries must be evaluated from both an accounting and funds-control perspective.
Closing the Series: The General Ledger Must Preserve the Story
Across these three installments, we followed obligations from undelivered orders to delivered orders, payment, and recovery.
We examined upward adjustments, downward adjustments, expenses, capitalized assets, liabilities, receivables, and disbursements.
Each stage introduced different accounting requirements.
An upward adjustment that was previously accrued is not the same as one recognized directly in paid status.
A downward adjustment that reduces an unpaid liability is not the same as collecting a refund of funds previously disbursed.
And recovering budgetary authority is not necessarily the same as obtaining authority to obligate it again.
A trial balance may reconcile to zero while still requiring careful examination of the transactions behind its balances.
Likewise, a balanced journal entry does not necessarily establish that the underlying accounting treatment is correct.
Correct accounting requires more than balancing the entry. It requires understanding the transaction.
The original obligation tells one part of the story. The adjustments tell another. Payment and recovery complete the financial lifecycle.
The general ledger should preserve that entire story — not simply the final balance.
The views expressed in this article are those of the author and do not necessarily reflect the views of any employer, client, agency, or organization. The account structures and examples referenced are simplified for illustrative purposes and do not represent guidance for any specific agency's accounting treatment.
About The Brookover Review
The Brookover Review is an independent publication dedicated to advancing federal financial management through practical insights, original frameworks, and thoughtful discussion. Subscribe to receive monthly bulletins, future articles, and original frameworks covering federal financial management, financial systems, audit readiness, and digital transformation.